RSS

Buying an Older Condo in BC: What Should You Look For?

Older condos can offer larger floor plans, better locations and more space for your money. But before buying one, it's important to understand what you're getting into.

When shopping for a condo, it's easy to focus on newer developments with modern finishes and the latest amenities. However, some of the best opportunities can be found in older buildings, particularly if you're looking for more space, a practical floor plan or an established neighbourhood.

Older condos often have features that are becoming harder to find in newer developments. Larger bedrooms, separate dining rooms, generous living spaces, plenty of storage and, in some cases, significantly more square footage for your money. You may also find buildings in established neighbourhoods with mature landscaping, convenient access to amenities and locations where new construction is limited.

Of course, buying an older condo also comes with considerations that extend well beyond the individual unit. When you purchase a strata property, you're also taking on a share of the building's maintenance responsibilities, financial obligations and future expenses. That's why understanding the condition of the building and how it's been managed over the years is so important.

Here are some of the things I recommend looking into when considering an older condo in British Columbia.

1. Look beyond the age of the building

Two condo buildings constructed in the same year can have remarkably different maintenance histories. One might have recently completed a major roofing project, replaced its plumbing and upgraded its elevators, while another could still have all three of those expenses ahead of it. Despite being the same age, their anticipated maintenance costs and the financial obligations facing their owners could be quite different.

I always encourage buyers to investigate what's already been replaced, what still needs attention and whether the strata has been proactive about maintaining its property. Major components such as the roof, building envelope, plumbing, windows, balconies, elevators and underground parking membranes can all involve substantial expenditures. You don't necessarily need to find a building where everything has already been replaced, but you should understand the condition of these components and what expenses could be coming.

For example, imagine you're considering two condos. One has a beautiful $75,000 interior renovation, complete with a new kitchen, bathrooms and flooring, but the building has aging plumbing and is approaching a major building-envelope project. The other has a dated interior that could use some cosmetic improvements, but the building has recently completed several major capital projects. Neither is automatically the better purchase, but the second might give you more control over when and how you spend money on improvements. With the first, you could be facing substantial building expenses that are largely outside your control.

2. Read the depreciation report and understand what it tells you

One of the most valuable documents when evaluating an older strata property is its depreciation report. This report assesses major building components, estimates their remaining useful lives and projects the costs of maintaining, repairing or replacing them over a 30-year period. In B.C., strata corporations with five or more strata lots are generally required to obtain a depreciation report every five years.

I wouldn't automatically be concerned about a depreciation report identifying substantial upcoming expenses. Every building eventually needs repairs, and older buildings will naturally have components approaching the end of their expected lifespans. What matters is whether the strata understands those expenses and has been planning for them. A building anticipating a $2 million roof replacement in five years might already have substantial funds set aside or an established financing strategy. Another building might have the same anticipated expense but little money saved and no clear indication of how the owners intend to pay for it.

It's also important to remember that depreciation reports are planning documents, not guarantees. Projected costs can change, components can deteriorate more quickly than expected and unforeseen repairs can arise. When reviewing a report, I like to compare its recommendations with the strata meeting minutes and financial statements to see whether the building has actually been following through on its maintenance plans.

3. A large contingency reserve fund doesn't always mean a financially healthy building

One of the first questions buyers often ask is how much money the strata has in its contingency reserve fund (CRF). This is money set aside to help pay for expenses that occur less frequently than regular operating costs, such as replacing a roof, upgrading an elevator or undertaking major building repairs. Having a substantial reserve is certainly encouraging, but the balance alone doesn't tell you nearly enough about the building's financial position.

Consider the following two hypothetical buildings.
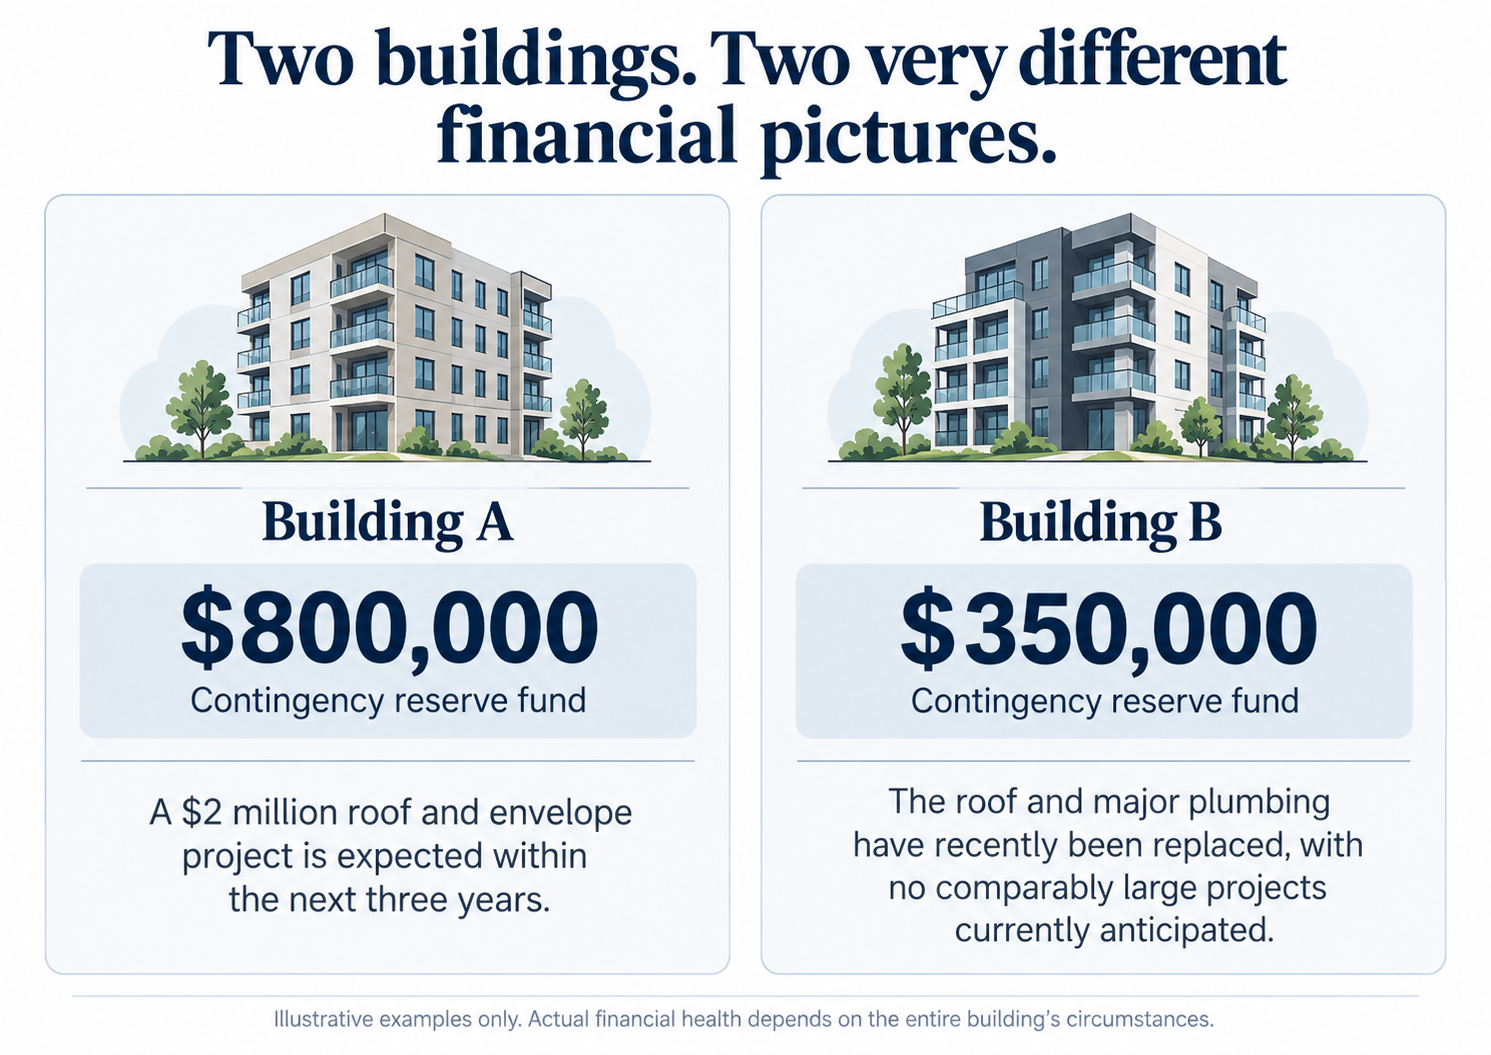
At first glance, Building A might appear to be in a stronger financial position because it has considerably more money available. However, once you account for its upcoming expenses, the picture changes. Building B may be in a more comfortable position because it has already completed some of its largest projects. Of course, we'd still need to examine the age and condition of its remaining components, future maintenance requirements and how much money the strata contributes to its reserve fund each year.

This is why I prefer to look at the contingency fund alongside the depreciation report, operating budget, financial statements and history of special levies. The amount of money a strata has saved is important, but understanding what it will need that money for is equally important.

4. The strata minutes can tell you a lot about how a building is managed

Strata meeting minutes are among the most revealing documents available to buyers. While financial statements show where money is being spent, meeting minutes can provide insight into how the strata identifies problems, makes decisions and manages ongoing maintenance. I recommend reviewing the available council meeting minutes along with the annual general meeting (AGM) and any special general meeting (SGM) minutes.

As you read through them, pay attention to recurring issues rather than focusing on every individual complaint or repair. For example, a mention of a leaking pipe in one meeting wouldn't necessarily concern me. However, if water leaks have been discussed repeatedly over the past two years, several insurance claims have been made and the council has been considering a complete plumbing replacement, that's something worth investigating further. Similarly, repeated discussions about a major project that owners continually vote against could indicate that necessary maintenance is being postponed.

The goal isn't to find a building with no problems. Every strata will encounter maintenance issues, particularly as its building ages. What I want to see is evidence that problems are being investigated, qualified professionals are being consulted and the strata is taking appropriate steps to address them. A building with a history of identifying and completing necessary work can present a very different picture from one that has been postponing difficult decisions for years.

5. Don't be fooled by low strata fees

Low monthly strata fees can look attractive when comparing properties, but they don't necessarily mean a building is less expensive to own over the long term. Strata fees pay for regular operating expenses and contributions to the contingency reserve fund. Depending on the building, these expenses might include insurance, landscaping, cleaning, management, utilities, amenities and ongoing maintenance.

A building that has kept its strata fees unusually low for years might be operating efficiently, or it might be underfunding future repairs. Imagine two similar buildings where one charges $350 per month and the other charges $500. The less expensive building initially looks appealing, but if its owners have consistently voted to keep fees low rather than adequately funding the contingency reserve, they could eventually face substantial fee increases or special levies. Meanwhile, the building with higher monthly fees may have been steadily accumulating money for upcoming projects.

Rather than automatically favouring the building with the lowest fees, I look at what those fees cover, how much is being contributed to the contingency reserve fund and whether the strata has an appropriate plan for its anticipated expenses. A well-maintained building costs money to operate, and understanding where that money goes is an important part of evaluating a purchase.

6. Understand special levies and their potential impact on your budget

Special levies are another important consideration, particularly when purchasing into a building with major projects approaching. A special levy is an additional amount owners are required to contribute toward a specific expense. These are commonly used when a major repair or replacement project cannot be fully funded through the regular operating budget or contingency reserve fund.

For example, imagine a 100-unit building that approves a $2 million building-envelope project. If that expense were divided equally among all 100 units, each owner would be responsible for $20,000. In reality, special levies are generally allocated according to unit entitlement or another legally applicable method, meaning some owners may pay considerably more or less than others.

For a buyer who has just used most of their available savings for a down payment, an unexpected $20,000 expense could be financially challenging. That's why it's important to investigate whether major projects are being contemplated and whether any special levies have already been approved. B.C.'s Form B Information Certificate discloses approved special levies with future payment obligations, but it won't necessarily tell you about every expense the strata might consider in the future. Those potential expenses often become apparent when reviewing the depreciation report, meeting minutes and other available building information.

If a special levy has already been approved, make sure you understand the payment schedule and how responsibility for the payments is being addressed in your purchase contract. Your real estate lawyer or notary can help clarify the financial obligations associated with a particular purchase.

7. Review the building's insurance

Insurance is another area that deserves attention when evaluating an older condo. Review the building's current coverage, insurance history and deductibles, particularly those relating to water damage. Depending on the building's claims history and other risk factors, deductibles can be substantial, potentially exposing individual owners to significant expenses if they're found responsible for a loss.

For example, imagine a dishwasher supply line fails in your condo and causes water damage to several units below. Depending on the circumstances, the strata may be able to recover its insurance deductible from you, even if you weren't negligent. Some strata insurance deductibles can reach hundreds of thousands of dollars, making appropriate personal condo insurance particularly important.

Before removing your purchase conditions, I recommend speaking with an insurance broker to ensure you can obtain appropriate coverage for the property. Your personal insurance should be considered alongside the building's policy, including coverage for your belongings, improvements to the unit, personal liability and potential strata deductible assessments. Previous claims or significant increases in the building's insurance premiums are also worth investigating.

8. Don't forget to evaluate the individual condo

While much of the due diligence involved in buying an older condo focuses on the building, the condition of the individual unit still matters. An older condo might have original appliances, aging plumbing fixtures, dated electrical components or flooring and cabinetry that have reached the end of their useful lives. These issues aren't necessarily deal-breakers, particularly if the property is priced accordingly, but they should be considered when establishing your renovation budget.

If the unit has already been renovated, it's worth understanding what work was completed, whether permits or strata approval were required and whether those approvals were obtained. A newly renovated kitchen doesn't necessarily mean the plumbing or electrical systems behind the walls have been upgraded. I also recommend obtaining a professional home inspection, which can identify visible issues within the unit and highlight areas that warrant further investigation.

Finally, don't overlook the strata bylaws and other practical considerations. If you have pets, plan to rent out the property or hope to undertake renovations, make sure you understand the applicable rules. Confirm how parking spaces and storage lockers are allocated and whether any alterations or improvements you're planning would require strata approval.

Final thoughts: older doesn't mean worse

Some older condos can be excellent purchases, offering floor plans, room sizes and locations that may be difficult to find in newer developments at a comparable price. I've also seen older buildings that have been exceptionally well maintained, with proactive strata councils, substantial upgrades and sensible financial planning. Conversely, even relatively new buildings can encounter significant maintenance problems or unexpected expenses.

The important thing is to look at the complete picture. A dated interior might be relatively straightforward to improve, while major building repairs can involve substantial costs and decisions outside your control. Before purchasing, take the time to understand what's already been done, what's likely coming next and whether the strata appears financially prepared to handle those obligations.

Buying an older condo isn't about finding a building that will never need repairs. Every building will eventually require maintenance and the replacement of major components. The goal is to understand those responsibilities before you purchase, rather than discovering them after you've moved in.

If you're considering buying an older condo in Coquitlam, Port Coquitlam, Port Moody or the surrounding area, I'd be happy to help you evaluate your options and review the strata documents so you can make a well-informed decision.

Jeremy Kyle, MBA

RE/MAX All Points Realty
www.kylerealestate.ca 

Read

What Buyers Should Ignore When Viewing a Home

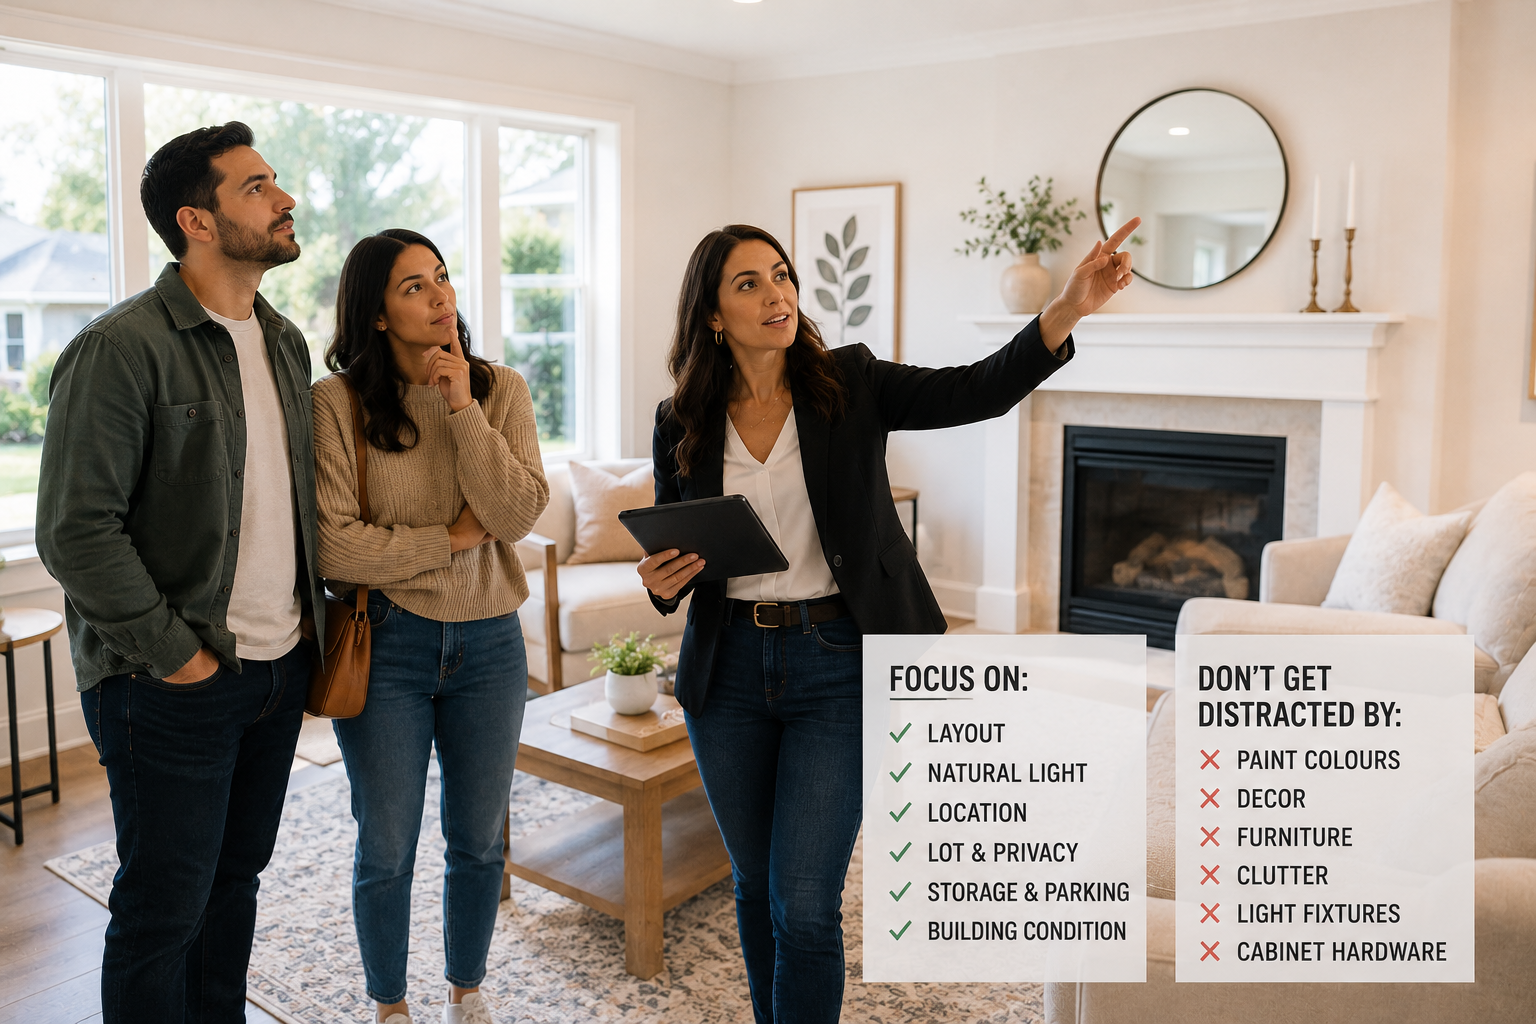
When you walk through a home, it’s easy to get distracted.

Maybe the paint colours are not your style. Maybe the furniture feels dated. Maybe the house is cluttered. Maybe the lighting is too dark, or the decor makes it hard to picture yourself living there.

Those things can affect how a home feels. But they don’t always affect whether the home is a good fit. Some of the things buyers notice first are also some of the easiest things to change.

Paint can be changed. Light fixtures can be replaced. Furniture goes with the seller. Cabinet hardware can be updated. Landscaping can be improved. Carpet can often be replaced. Even a room that feels awkward because of the current furniture layout may function much better with your own setup.

The bigger things matter more.

Location. Layout. Lot. Natural light. Parking. Storage. Suite potential. Strata condition. Building systems. Roof, windows, plumbing, electrical, drainage, exterior maintenance, and overall structure. Those are the things that can have a much bigger impact on your day-to-day life, your costs, and your future resale. This is why it’s important to look past surface-level distractions.

A home that doesn’t show perfectly may still be a very good opportunity. In fact, some buyers overlook homes simply because they can’t see past cosmetic issues. That can create opportunity for buyers who are willing to look more carefully.

On the other hand, a home that shows beautifully is not automatically the best choice.

Great staging, fresh paint, and nice furniture can make a home feel impressive. But buyers still need to look at the details that matter. Is the layout functional? Are there expensive repairs coming? Is the price supported by comparable sales? Does the home actually fit your needs?

When I walk through homes with buyers, I try to help them separate emotion from substance. I want them to notice how the home feels, but I also want them to understand what they are really buying.

Some flaws are easy to fix.
Some flaws are expensive.
Some flaws are just distractions.

Knowing the difference can save you from passing on a good home — or falling for the wrong one.

The goal is not to ignore everything. The goal is to know what deserves your attention.

Read

What Does “The Market” Actually Mean for You?

People talk about “the real estate market” all the time.

The market is up.
The market is down.
It’s busy.
It’s slow.
It’s a buyer’s market.
It’s a seller’s market.

But here’s the thing: there really isn’t just one market.

When someone asks me, “How’s the market?” my answer is usually, “It depends.”

And I know that can sound like a bit of a non-answer, but it’s actually the most accurate one.

A detached home in Coquitlam can be experiencing a completely different market than a condo in Port Coquitlam. A townhouse in Maple Ridge may be getting strong interest while a higher-end detached home nearby sits for weeks. A nicely renovated family home in a popular school catchment can attract multiple buyers, even when the headlines are telling you the market is slow.

Real estate is incredibly local. Sometimes it’s even local down to the street, the price range, or the type of home. That’s why I always caution people against putting too much weight on broad headlines.

You might read that prices are falling, while the type of home you own is holding its value quite well. You might hear that it’s a buyer’s market, but if you’re trying to buy a very specific home in a neighbourhood with almost no inventory, it may not feel like one at all. Or you might hear that sales are slow, while a well-priced, well-presented home gets a lot of attention within its first week on the market.

That’s where context matters.

For buyers, understanding your particular market helps you know how you should approach an offer. Do you need to act quickly? Is there likely to be competition? Is there room to negotiate? Can you afford to wait and see? Those answers aren’t the same for every property.

For sellers, it’s just as important. Knowing what’s happening with homes that actually compete with yours helps us make better decisions around pricing, preparation, marketing, and expectations. It helps answer questions like:

How many similar homes are for sale right now?

How quickly are they selling?

Are buyers paying close to asking price?

What condition are the competing homes in?

Are certain price ranges moving better than others?

Are buyers responding differently to renovated homes versus homes that need work?

Those are the things that tell us what your market looks like.

A general market update can still be useful, of course. It gives us a sense of the bigger picture. But it becomes much more valuable when we narrow it down to your actual situation. That means looking at things like:

  • Your property type

  • Your neighbourhood

  • Your price range

  • The homes you’re competing against

  • Recent comparable sales

  • Current inventory

  • Buyer demand

  • Condition and presentation

  • Timing

So, when someone asks me, “How’s the market?” the most useful answer is rarely just “good” or “bad.” It’s “Let’s look at the part of the market that actually matters to you.” Because at the end of the day, the market that matters isn’t the entire Lower Mainland. It’s the market for your home, your budget, your neighbourhood, and your goals.

And that’s where good real estate advice becomes valuable—not just repeating headlines, but helping you understand what they actually mean for you.

Read

Why Your Home’s Assessed Value Is Not the Same as Market Value

Every year, homeowners receive their property assessment, and one of the most common questions is:

“Is this what my home is worth?”

The short answer is no — not necessarily.

Your assessed value and your market value are not the same thing.

An assessed value is used for property tax purposes. It is based on a valuation date and uses broad data to estimate the value of properties across an area.

Market value is what a buyer is willing to pay for your home in the current market.

Those two numbers can be close, but they can also be very different.

There are several reasons for that.

First, assessments are based on a specific point in time. By the time you receive the assessment, the market may have changed. Buyer demand, interest rates, inventory, and local conditions may all be different.

Second, assessments may not fully capture the details of your specific home.

They may not reflect recent renovations, condition, layout, views, suite potential, updates, curb appeal, privacy, floor plan, or how buyers feel about the property in person.

Two homes on the same street may have similar assessments but sell for very different prices because of condition, layout, lot usability, exposure, or updates.

Third, market value is influenced by competition.

If there are very few similar homes for sale, buyers may be willing to pay more. If there are many competing homes, buyers may have more choices and negotiate more strongly.

That is why your neighbour’s assessment, your assessment, and your actual market value can all be different.

For sellers, this is important because pricing based only on assessed value can lead to mistakes.

If the assessment is too low, you could underprice. If it is too high, you could overprice and sit on the market.

For buyers, it is also important. A home listed above assessed value is not automatically overpriced. A home listed below assessed value is not automatically a deal.

You need to look at recent comparable sales, current competition, property condition, location, and buyer demand.

The assessment is one piece of information.

It is not the full story.

If you want to understand what your home may actually sell for, you need a current market evaluation based on real-time conditions and the details that make your property unique.

Read

Why the Highest Offer Is Not Always the Best Offer

When selling your home, it’s natural to focus on price.

If one buyer offers more than everyone else, it can feel like the obvious choice.

But the highest offer is not always the best offer.

A real estate offer is made up of more than just the purchase price. The terms matter too.

A slightly lower offer with stronger terms may sometimes be more attractive than a higher offer with more risk.

For example, sellers need to consider:

  • Subject conditions

  • Financing strength

  • Inspection terms

  • Deposit amount

  • Completion and possession dates

  • Included items

  • Buyer motivation

  • The likelihood of the deal actually firming up

A high offer with a long list of subjects may not be as strong as it looks. If the buyer still needs financing approval, an inspection, document review, or other conditions, there is still a chance the deal may not proceed.

That does not mean subject offers are bad. In many situations, they are completely normal and reasonable.

But sellers need to understand the full picture before deciding which offer to accept.

For example, one buyer might offer more money but need several weeks to remove subjects. Another buyer might offer slightly less but have a stronger deposit, better dates, and fewer conditions. Depending on the seller’s situation, the second offer may actually be the safer and better choice.

Dates can matter too.

If the seller has already bought another home, the completion date may be very important. If the seller needs extra time to move, possession terms may matter. If the property is tenanted, timing and notice requirements may need to be considered carefully.

This is where strategy matters.

My job is to help sellers compare offers properly, not just react to the biggest number.

We look at price, terms, risk, timing, and the likelihood of a successful closing.

Sometimes the highest offer is the best offer.

But not always.

The best offer is the one that gives the seller the strongest overall result based on their goals, timeline, and risk tolerance.

That’s the difference between simply receiving offers and properly evaluating them.

Read

How Many Homes Should You See Before Buying?

When you’re looking to buy a home, it’s easy to think the best strategy is to see as many properties as possible.

After all, more homes means more options, right?

Not always.

In fact, seeing too many homes can sometimes make the process harder, not easier. I’ve worked with buyers who start to feel overwhelmed, second-guess themselves, or lose track of what actually matters most to them. After a while, the homes can start blending together.

Was that the one with the great kitchen but no yard?
Or the one with the basement suite but the awkward layout?
Or the one that checked most of the boxes but felt too far from school?

Buying a home is a big decision. But seeing 50, 75, or 100 homes doesn’t always lead to more confidence. Sometimes it leads to more confusion.

The Goal Isn’t to See Every Home

The goal is to see the right homes.

A good home search should not feel like wandering through every available listing and hoping one of them magically feels right. It should become more focused as you go.

At the beginning, you may need to see a few different options to understand what your budget can actually get you. You might compare neighbourhoods, layouts, property types, or renovation levels. That’s normal.

But once we start learning what matters most to you, the search should become sharper.

That might mean narrowing in on:

  • The right neighbourhoods

  • The type of home that fits your lifestyle

  • The features you actually use every day

  • Your must-haves versus nice-to-haves

  • The trade-offs you are willing to make

  • What feels right for your family, not just what looks good online

This is where the process becomes much more productive.

Too Many Showings Can Lead to Decision Fatigue

There is such a thing as seeing too much.

When buyers see home after home without a clear plan, it can lead to decision fatigue. Every property has pros and cons. Every home requires some level of compromise. If you are comparing too many options at once, it becomes harder to make a confident decision.

Instead of asking, “Is this the right home for us?” buyers can start asking, “What if something better comes up?”

That question can keep people stuck.

There will almost always be another listing. But the right home search is not about chasing perfect. It’s about finding the best fit based on your needs, budget, timing, and priorities.

My Job Is to Help You Focus

As your Realtor, my job is not just to send you listings and unlock doors.

My job is to help you make sense of the market.

That means helping you narrow down what you really want, understand what is realistic in your price range, and identify which homes are actually worth your time.

Before we book showings, I want to understand:

  • What problem are you trying to solve with this move?

  • What does your home need to do for your day-to-day life?

  • What are your non-negotiables?

  • Where are you flexible?

  • What trade-offs make sense?

  • What would make a home a “no” right away?

From there, we can create a more focused showing plan.

Instead of touring every home that kind of fits, we focus on the ones that truly deserve a closer look.

Focused Showings Save Time and Reduce Stress

A focused showing tour is not about rushing the process. It’s about making the process clearer.

When we tour the right homes, you can compare them more effectively. You start to notice patterns. You understand what you like, what you don’t, and what is worth paying for.

Sometimes buyers find the right home quickly. Sometimes it takes longer. Both are okay.

The number of homes you see is not the measure of whether you made a good decision.

What matters is whether you had the right information, understood your options, and felt confident in the choice you made.

So, How Many Homes Should You See?

There is no perfect number.

Some buyers find the right home after seeing five properties. Others need to see twenty. Some need more time because they are relocating, changing property types, or still figuring out what matters most.

But seeing more homes is not automatically better.

The better question is:

Are we seeing the right homes?

If the answer is yes, the process becomes much less overwhelming and much more useful.

A thoughtful home search should help you gain clarity, not create confusion.

Thinking About Buying?

If you’re starting to think about buying a home, the first step isn’t necessarily booking a dozen showings.

The first step is getting clear on what you need, what you want, and what makes sense for your life.

That’s where I can help.

Whether you’re buying your first home, upsizing for more space, or trying to figure out which neighbourhood is the best fit, I can help you narrow the search and make the process feel a lot less overwhelming.

Read

GST Rebate for First-Time Home Buyers Is Now in Effect: What Buyers Need to Know

There is an important new change for home buyers in Canada as of March 20, 2026. The federal First-Time Home Buyers’ GST/HST rebate is now in effect, and for eligible buyers, it could mean significant savings on the purchase of a qualifying new home. In some cases, the savings can be as much as $50,000.

At a high level, the new rebate eliminates the federal GST on qualifying new homes priced at $1 million or less. For qualifying homes priced between $1 million and $1.5 million, the rebate is reduced on a sliding scale. Homes priced at $1.5 million or more do not qualify for this rebate. The CRA gives the example of a $1.25 million home qualifying for 50% of the maximum rebate, or $25,000.

Who is this for?

This rebate is designed for eligible first-time home buyers. According to the CRA, a first-time buyer generally must be at least 18 years old, must be a Canadian citizen or permanent resident, and must not have lived in a home they or their spouse/common-law partner owned as their primary residence in the calendar year of possession or the previous four calendar years.

The property must generally be:

  • Newly built or substantially renovated

  • Intended as the buyer’s primary place of residence

That means this rebate is mainly about new construction, not the typical resale home purchase.

What homes could qualify?

The CRA says the rebate may apply in situations where an eligible first-time buyer:

  • buys a newly built or substantially renovated home from a builder

  • builds or substantially renovates a home for their own use

  • buys certain qualifying homes on leased land

  • buys a qualifying share in a co-op

  • in some cases, buys a qualifying mobile or floating home

For most buyers reading this, the most relevant category will be the purchase of a new condo, townhouse, or detached home from a builder.

What dates matter?

This is one of the biggest details.

The rebate generally applies where the agreement of purchase and sale was entered into on or after March 20, 2025, and before 2031. The construction or substantial renovation must generally begin before 2031 and be substantially completed before 2036, with transfer of ownership before 2036 in the applicable cases.

So while the rebate is in effect today, some buyers who already signed a qualifying agreement after March 20, 2025 may also be able to benefit, depending on their situation. The CRA says applications are open, although it is still updating filing systems for some purchase agreements signed between March 20, 2025 and May 26, 2025.

Does this apply to resale homes?

In most cases, no.

Typical resale homes are generally not subject to GST, so this new rebate does not usually change the math on a normal resale purchase. Instead, this is a policy that could make new homes more attractive and more affordable for eligible first-time buyers.

Why this matters for buyers in our market

For buyers in markets like Coquitlam, Port Coquitlam, Port Moody, Maple Ridge, and Pitt Meadows, affordability is always part of the conversation. New construction can sometimes feel just out of reach once GST is added in. This new rebate could make certain projects, presales, or newly built homes more attainable for first-time buyers who qualify.

It will not suddenly make every new home affordable, and it does not apply in every case. But it is a meaningful change that could influence:

  • whether buying new makes more sense than buying resale

  • whether a buyer chooses to move sooner

  • how a buyer sets their price range

  • how much cash they need at closing

Final thoughts

This is one of the more important buyer-focused housing changes we’ve seen in a while. If you are a first-time buyer, or if someone in your family is planning their first purchase, it is worth looking closely at whether this rebate could apply.

The key takeaway is simple: as of March 20, 2026, eligible first-time buyers may now be able to save up to $50,000 on a qualifying new home through the federal GST/HST rebate.

If you want help figuring out whether a specific property, presale, or purchase plan could qualify, I’d be glad to help you work through it.

Read

What the Bank of Canada’s Interest Rate Cut Means for Coquitlam Homeowners & Home Buyers

On September 17, 2025, the Bank of Canada cut its policy interest rate, lowering borrowing costs modestly. For folks in Coquitlam, Port Coquitlam, Port Moody (the Tri-Cities), this cut has real effects — especially given how high home prices are locally, and how those translate into mortgage payments.

What the Rate Cut Actually Means Locally

  • Lower cost for variable-rate mortgages: If you have a variable or adjustable-rate mortgage, your interest component will likely drop by roughly 0.25% (or perhaps slightly more or less depending on lender). That translates into lower monthly payments immediately (or upon your next reset).

  • Fixed rate renewals & new fixed mortgages may fall: Fixed mortgage rates are tied to bond yields and lender risk assumptions, which respond more slowly to policy rate changes. But expect that over coming weeks / months, fixed rates for new mortgages or renewals will trend downward somewhat.

  • Improved affordability but still stretched: Even with rate cuts, high principal amounts (because of high home prices) mean payments remain large. For many buyers, the biggest obstacle remains the down payment, debt servicing, property taxes etc., not only the mortgage rate.

  • Competition may pick up: Lower rates often bring more buyers into the market, especially those previously waiting out high rates. Could increase bidding, particularly on more affordable/townhouse/condo options.

  • Opportunity for refinancing or switching: Homeowners with older mortgages at higher rates might look to refinance, or those coming up for renewal can shop around. Variable vs fixed decisions become more interesting: if further rate cuts are expected, variable might offer savings, but fixed gives certainty.

Sample Scenarios: Coquitlam

Below are estimates of the monthly mortgage payment differences before vs after a 0.25% rate cut (variable/adjustable rate dropping by 0.25%) for different home types in Coquitlam. Assumes a 25-year amortization, 20% down payment, interest rate dropping from say 4.50% → 4.25% (variable) for simplicity.

Notes:
• The “mortgage amount” assumes 20% down, thus 80% is financed.
• These are estimates; actual payments depend on lender, mortgage fees, whether the rate is fixed vs variable, property tax, insurance, strata fees (for condos/townhouses), etc.
• The rate drop is only for the interest portion; principal + amortization profile remains the same.

These savings might not sound huge relative to total payment, but over time they add up — and especially help those on the margins: people renewing, those with variable mortgages, or people trying to fit into tighter budgets.

What Does This Mean For You?

If you own:

  • Check if your mortgage is coming up for renewal: rates may be lower now or soon.

  • If you have variable rate, expect lower payments or ask your lender what the reset might look like.

If you’re buying:

  • Factor the rate cut into affordability calculations. Your borrowing costs are cheaper, which helps your qualifying power.

  • Compare fixed vs variable carefully, especially if you expect more cuts, or if your budget can absorb rate fluctuations.

  • Townhouses/condos may become more appealing as the payment gap with detached narrows a bit (though price differences remain large).

The Bottom Line

The Bank of Canada’s rate cut gives Coquitlam & Tri-Cities residents a bit of a break — especially for variable mortgages and renewals. Savings of $100-300+ per month are possible depending on home type. But while helpful, this cut doesn’t dramatically change the affordability picture given high home prices. For many, the key remains balancing loan size, down payment, and monthly carrying costs.

Every homeowner’s situation is a little different, and this rate cut will affect people in different ways depending on their mortgage and their goals. If you’re curious how it might impact you, I’d be glad to share a local market update and connect you with trusted mortgage brokers who can walk you through your options. Sometimes just having the right information—and the right people in your corner—can make all the difference.

Read

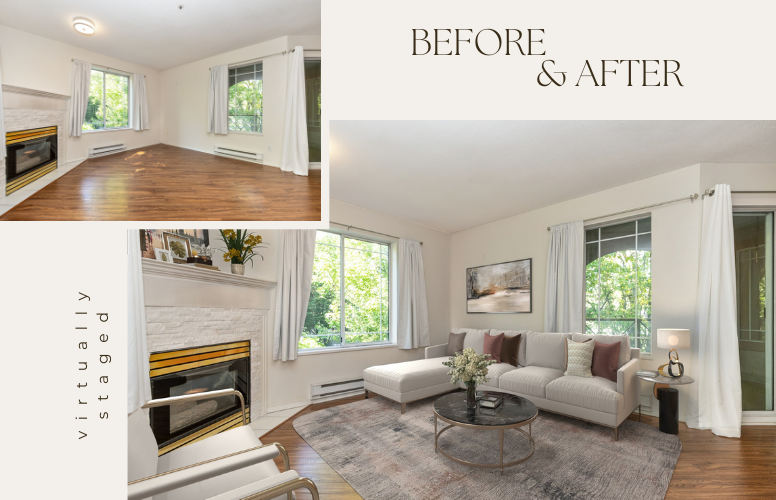
The Big Impact of Smart & Virtual Staging

When buyers scroll through listings, they make split‑second decisions: Does this feel like my home? Minimal staging and smart virtual staging help the right buyers say “yes” faster—without the cost and logistics of full furniture staging. Here’s how our approach elevates your sale price, accelerates showings, and sets our listings apart.


What We Mean by “Minimal Staging”

We focus on high‑impact accessories and light styling—not moving trucks full of furniture. Think:

  • Fresh throw pillows and textured throws to soften spaces

  • Greenery and simple planters to add life and scale

  • Mirrors and art to create light and sightlines

  • Layered lamps, books, and trays for warmth and lifestyle cues

  • Entryway and bathroom refreshes (towels, soap sets, hardware touch‑ups)

These updates are quick, affordable, and purpose‑built to improve photos and in‑person flow.

Why It Works (The Buyer Psychology)

  • Reduces mental friction. Clutter and overly personal décor make buyers pause. Clean, neutral styling invites them to picture their life in the space.

  • Clarifies scale and function. A mirror or plant can define a nook or brighten a hallway, guiding the eye and helping buyers understand room size.

  • Boosts perceived care. Small, coordinated touches signal a well‑maintained home. That improves confidence and perceived value.

  • Better photos = more traffic. Most buyers meet your home online first. Minimal staging makes every image scroll‑stopping.


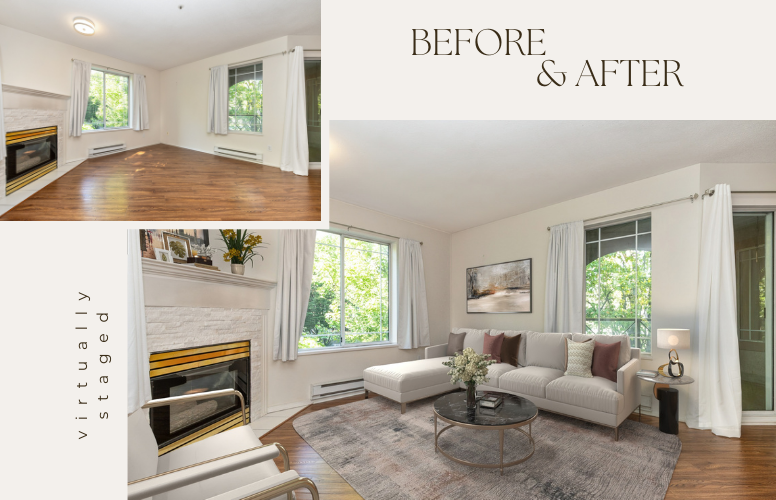
Virtual Staging for Vacant Homes

Empty rooms can feel cold and smaller than they are. Virtual staging solves that—beautifully.

How we use it:

  • We digitally furnish vacant rooms to show scale, flow, and style options.

  • We can create multiple looks (modern, family‑friendly, minimalist) tailored to your likely buyer profile.

  • Every virtually staged photo is clearly labeled in marketing materials for full transparency.

The buyer benefits:

  • Understand furniture placement and room purpose instantly

  • See how an office, nursery, media room, or gym could work

  • Spark ideas they bring into showings, increasing engagement and offers

The seller benefits:

  • No rental furniture costs or logistics

  • Faster to market with stronger online appeal

  • Flexible designs to match target demographics

Pro tip: We include the original empty room photo alongside the virtually staged version online so buyers can imagine both possibilities.


What Sets Us Apart

1) Complimentary, Minimal Staging Using Your Items
Whenever possible, we re‑style with what you already own and supplement with select accessories (pillows, throws, plants, art, mirrors). It’s efficient, sustainable, and cost‑smart.

2) Strategic, Buyer‑Led Design
We start by defining the most likely buyer: first‑time homeowners, upsizers, downsizers, or investors. Then we tailor spaces to resonate with that buyer group.

3) Marketing Tech That Multiplies Results
From pro photography and video to 3D tours and virtual staging, we build an integrated campaign that increases visibility across MLS, our website, social media, and targeted email. We monitor interest and refine quickly.

4) Elegant Transparency
We clearly label virtually staged images and ensure everything in‑home matches expectations—no surprises.

5) Skilled Negotiation & Presentation
Staging gets buyers to the door; our pricing strategy and negotiation training help you capture full value once they’re there.


Rooms & Moments We Prioritize

  • Front entry: first impressions, scent, and sightline to the main living area

  • Living room: lighting layers, textures, a strong focal point (art or mirror)

  • Kitchen: clear counters, one or two lifestyle vignettes (coffee station, wood board)

  • Primary bedroom: hotel‑style bedding, lamps, and calm art

  • Bathrooms: white towels, neutral décor, spa‑like simplicity

  • Small or awkward spaces: mirror + plant or a clear alternate use (reading nook, homework station)


Before We Start: Seller Prep Checklist

  1. Declutter & donate (we can advise where it counts most)

  2. Deep clean (windows, baseboards, light fixtures, vents)

  3. Minor repairs (loose handles, scuffs, burnt bulbs)

  4. Neutralize strong colours where practical

  5. Curb appeal (sweep, weed, fresh doormats, seasonal planters)


How Our Process Works

Step 1: Walk‑Through & Buyer Targeting
We identify your likely buyer and the 3–5 key scenes we must nail for photos.

Step 2: Minimal Staging Plan
A room‑by‑room list of accessories and tweaks, using a mix of your items and ours.

Step 3: Photo Day & Virtual Staging
We capture each room in its best light and apply virtual staging to vacant spaces. All images are clearly labeled.

Step 4: Launch & Optimize
We go live across channels, track engagement, and adjust marketing elements to maximize showings.


Results You Can Expect

  • Cleaner, brighter photos that stop the scroll

  • More showings in the first two weeks (the most important window)

  • Clearer value story in person—buyers “get” the layout and lifestyle

  • Stronger offers driven by confidence and emotional connection


FAQs

Is minimal staging worth it if I’m still living in the home?
Yes. Small changes (pillows, throws, lamps, art, greenery) dramatically improve photos and daily showings—with minimal disruption.

Will buyers feel misled by virtual staging?
We label all virtually staged photos and also provide the original images. Buyers appreciate the clarity and the ideas.

How long does this take?
Most minimal staging can be completed within a couple hours, followed by photography, videography, and listing launch shortly after.


Ready to List Smarter—Not Harder?

If you’re considering selling in the Lower Mainland, let’s talk about a staging plan tailored to your ideal buyer and let’s get you moving!

Jeremy Kyle, MBA
Associate Broker, RE/MAX All Points Realty
kylerealestate.ca

Read

Preventing Mold and Moisture Issues on the West Coast of B.C.

Living on the beautiful west coast of British Columbia comes with its perks—stunning landscapes, temperate weather, and lush greenery. However, the region’s high levels of rainfall and humidity during the rainy season can create the perfect conditions for mold and moisture issues in your home. Left unchecked, these problems can lead to structural damage and health concerns. Here’s how to manage dampness and keep your home dry and healthy throughout the season.


Why Mold and Moisture Are Common on the West Coast

The Pacific Northwest’s rainy climate means homes are frequently exposed to high humidity levels and persistent dampness. Poor ventilation, leaky windows, and inadequate insulation can worsen these issues, creating environments where mold thrives. Common signs of moisture problems include condensation on windows, musty odors, and discoloration on walls or ceilings.


Practical Tips to Prevent Mold and Moisture

Here are some effective ways to tackle moisture issues and safeguard your home:

1. Improve Ventilation

  • Use Exhaust Fans: Ensure kitchen and bathroom fans are vented to the outside and run them during and after cooking or showering.

  • Open Windows: On dry days, open windows to allow fresh air to circulate and reduce indoor humidity.

  • Invest in a Dehumidifier: A portable dehumidifier is a great tool for reducing moisture in problem areas like basements.

2. Maintain Your Roof and Gutters

  • Inspect Your Roof Regularly: Look for missing or damaged shingles that can allow water to seep in.

  • Clean Gutters and Downspouts: Clear away leaves and debris to prevent water from pooling near your home’s foundation.

3. Seal Windows and Doors

  • Check for Leaks: Inspect windows and doors for drafts or water infiltration, especially after heavy rain.

  • Reapply Weatherstripping and Caulk: Replace worn weatherstripping and apply caulk to seal any gaps where moisture might enter.

4. Manage Indoor Humidity

  • Keep Humidity Levels Low: Aim for indoor humidity levels between 30-50%. You can use a hygrometer to monitor this.

  • Avoid Over-Drying Laundry Indoors: Hang wet clothes in a well-ventilated space or use a dryer vented to the outside.

5. Address Water Intrusion Immediately

  • Dry Wet Areas Quickly: Clean up spills and leaks as soon as possible to prevent water from soaking into floors or walls.

  • Fix Plumbing Leaks: Check under sinks and around pipes regularly for drips or pooling water.

6. Use Mold-Resistant Materials

  • Choose Mold-Resistant Paints: When repainting, use paints formulated to resist mold growth in humid environments.

  • Install Vapor Barriers: Consider using vapor barriers in crawl spaces or basements to prevent moisture from seeping in.


What to Do if You Find Mold

If you discover mold in your home, act quickly:

  • For Small Areas: Clean visible mold with a solution of water and vinegar or a commercial mold cleaner. Wear gloves and a mask to protect yourself.

  • For Larger Issues: Consult a professional mold remediation service to ensure the problem is fully addressed and doesn’t return.


Stay Ahead of the Rainy Season

Proactively managing moisture in your home can prevent costly repairs and keep your living environment safe and comfortable. By following these steps, you can enjoy the beauty of the west coast of B.C. without worrying about mold and moisture issues.

If you’d like more tips or need recommendations for local home maintenance experts, feel free to reach out—we’re here to help!

Read

Understanding Canada's New Mortgage Reforms: Opportunities and Cautions

In recent years, soaring home prices have placed homeownership out of reach for many, particularly Millennials and Gen Z. Addressing this, today the Canadian government announced significant mortgage reforms aimed at making homeownership more attainable. While these changes bring much-needed relief, it's important to approach them with a full understanding of both their benefits and potential unintended consequences.

Key Changes in Mortgage Rules

1. Extended Mortgage Amortizations:
Effective December 15, 2024, the availability of 30-year mortgage amortizations will be expanded to all first-time homebuyers and buyers of new builds. Initially restricted to new builds for first-time buyers, this extension allows for lower monthly payments, making it financially easier for new buyers to step into the housing market.

2. Increased Insured Mortgage Cap:
To reflect the reality of rising home prices, the cap for insured mortgages will increase from $1 million to $1.5 million. This adjustment, also effective December 15, 2024, helps more Canadians qualify for mortgages with a down payment below 20%. The change in down payment requirements could significantly impact buyers’ ability to afford homes in higher-priced markets.

Unintended Consequences to Consider

Increased Demand and Higher Prices:
While these reforms aim to make homeownership more affordable, they could inadvertently increase demand without a corresponding rise in housing supply. This imbalance can drive up prices, potentially making homes less affordable—the very issue these policies seek to mitigate.

Encouraging Higher Debt Levels:
Longer amortization periods mean smaller monthly payments but also result in more interest paid over the life of the loan. This might tempt buyers to take on larger loans than they can comfortably afford in the long run, increasing their overall debt burden and financial risk.

Supporting Measures and Consumer Protections

In addition to these financial reforms, the government is rolling out further protections for consumers, such as:

  • Renters’ Bill of Rights and Home Buyers’ Bill of Rights: These initiatives aim to protect consumers from unfair practices, simplify leases, and enhance transparency in the housing market.

  • Canadian Mortgage Charter: Revised to allow insured mortgage holders to switch lenders at renewal without a new stress test, fostering better mortgage deals and potentially lower interest rates.

Financial Empowerment for Buyers

The government is not just making it easier to buy homes but also helping Canadians save towards this goal:

  • Tax-Free First Home Savings Account: Allows up to $8,000 annual contributions, aiding Canadians in gathering funds for a down payment.

  • Enhanced Home Buyers’ Plan: Increases the limit to $60,000, leveraging RRSP contributions to enhance down payment savings.

A Vision for Expanding Homeownership

These mortgage reforms are part of Canada's ambitious plan to address the housing shortage and improve affordability. However, as prospective homebuyers navigate these changes, it's crucial to consider both the immediate financial relief they offer and the broader economic implications they might trigger. By doing so, Canadians can make informed decisions that align with both their personal financial situations and the evolving market dynamics.

Read

Understanding the Changes to BC's Residential Tenancy Act: What Landlords Need to Know

Significant amendments to the Residential Tenancy Act (RTA) are on the horizon with the implementation of Bill 14 – 2024: Tenancy Statutes Amendment Act. These changes are designed to increase compliance with eviction provisions and prevent bad-faith evictions, with some measures having taken effect on July 18, 2024, and others to be phased in over time. Here’s what current landlords and prospective investment property buyers in British Columbia need to know about navigating tenant evictions under the new regulatory landscape.

Key Changes in Effect Since July 18, 2024

1. Landlord Use Web Portal

One of the major changes introduced by Bill 14 is the creation of the Landlord Use Web portal that launched on July 18. Landlords intending to evict tenants for personal or caretaker use must now generate a Notice to End Tenancy through this portal. This requirement aims to enhance transparency and accountability, reducing instances of bad-faith evictions.

The portal will also enable the Residential Tenancy Branch to conduct post-eviction compliance audits, ensuring that landlords follow through with their stated intentions. This increased scrutiny aims to safeguard tenants' rights and maintain trust in the eviction process.

2. Extended Notice Periods

As of July 18th, the notice period for evictions due to personal or caretaker use increased from 2 months to 4 months. This change gives tenants more time to find alternative housing, reflecting a more tenant-friendly approach in the legislative amendments.

Future Changes to Monitor

1. Prohibition on Non-Residential Conversions

Bill 14 will eventually repeal Section 49(6)(f) of the RTA, which allows evictions for converting rental units to non-residential uses. This section will be replaced with a prohibition on such conversions, except for specific uses prescribed by regulation. The timing of this change is not yet determined, and landlords considering such conversions should stay informed about the forthcoming regulations.

2. Extended Use Requirement for Personal or Caretaker Use

The duration for which landlords must use a rental unit for personal or caretaker purposes after evicting a tenant will increase from 6 months to 12 months. Failure to comply with this requirement could result in landlords being liable to pay 12 months' rent as compensation to the evicted tenant. The exact implementation date for this change is yet to be announced.

Implications for Landlords and Buyers

Increased Accountability and Transparency

The introduction of the Landlord Use Web portal and the extended notice periods significantly impact how landlords must approach tenant evictions. The portal not only serves as a tool for issuing notices but also as a compliance mechanism, ensuring landlords adhere to the stipulated eviction reasons.

Legal and Financial Risks

Landlords must be aware of the heightened legal and financial risks associated with non-compliance. The penalties for bad-faith evictions—such as paying 12 months' rent to the evicted tenant—underscore the importance of genuine intent and adherence to the new regulations.

The extended four-month notice period for evictions also has significant implications for mortgage approvals, creating new legal and financial risks for landlords and potential property buyers.

Interest Rate Holds and Mortgage Approvals

  • Interest Rate Holds: Typically, interest rate holds last for 90-120 days. With the extended notice period, buyers might face the expiration of their interest rate hold, leaving them uncertain about the ultimate rate or payment, which could jeopardize their ability to afford the mortgage at closing time.

  • Approval Based on Current Rates: Mortgage approvals based on current rates could be invalidated if interest rates fluctuate during the extended notice period. This uncertainty can leave buyers unable to secure the necessary funds to complete the purchase.

  • Owner-Occupied Purchases: Lenders may be reluctant to approve a mortgage if a tenant is still present, complicating the financing process for buyers who intend to occupy the property.

Impact on Insured Mortgages and Investors

  • Insured Mortgages: For insured or “high ratio” mortgages, which occurs when a buyer has a down payment of less than 20%, the presence of a tenant reclassifies the property as a rental, which can lead to financing declines. This issue disproportionately impacts first-time buyers who rely on insured mortgages to enter the housing market.

  • Investor Challenges: Investors already facing cash flow issues due to rising interest rates will find it even more challenging to sell tenanted properties. The difficulty in accessing properties and the extended notice period reduces the appeal to potential buyers, exacerbating the housing supply shortage.

Strategic Planning for Property Investments

Prospective investment property buyers should factor in these changes when planning acquisitions. The amendments emphasize tenant protection, which could influence the timelines and strategies for property redevelopment or repurposing. It is crucial for investors to consult with legal and property management professionals to navigate these changes effectively.

Unintended Consequences

The impact of these changes, especially the effect of the new 4 month notice period for eviction on financing and mortgage approvals, may have several unintended consequences if these issues are not addressed.

  • Fewer Rentals: Landlords may be less inclined to rent out properties due to the increased complexity and risks involved in evicting tenants for personal or caretaker use.

  • Reduced Buyer Interest: Potential buyers may be unwilling to purchase tenanted properties due to the uncertainty and complications associated with the extended notice period.

  • Longer Closing Periods: The extended notice period can lead to longer closing periods, increasing the risk of transactions collapsing at the last minute.

  • Decreased Housing Availability: Ultimately, these factors could lead to less housing availability, contradicting the goal of increasing the housing supply.

This policy, while well-intentioned, needs reassessment to avoid punishing small real estate investors and further complicating the already challenging housing market in the lower mainland. Landlords and potential property buyers must navigate these changes carefully, considering the new risks and planning accordingly to avoid financial pitfalls.

Conclusion

As the provincial government strives to enhance the stability and affordability of rental housing, the amendments introduced by Bill 14 represent a significant shift in the regulatory landscape.Landlords must stay informed and comply with these changes to avoid potential penalties and ensure fair treatment of tenants. By understanding and adapting to these new requirements, landlords can better manage their properties and maintain positive tenant relationships.

With these changes, it’s more important than ever for landlords to work closely with property managers and legal advisors to ensure compliance and strategic planning in the evolving rental market in British Columbia.

Read
Reciprocity Logo The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.